Methodological approaches and practical algorithms for consolidating the financial statements of a group of companies under IFRS
This study examines the specific features of determining the composition of a group of companies based on control criteria and distinguishes between accounting approaches for subsidiaries, associates, and joint ventures. The study considers the accounting treatment of business acquisitions, the measurement of identifiable net assets, and the calculation of goodwill, bargain purchase gains, and non-controlling interests. The main stages of preparing consolidated financial statements are analyzed, including the line-by-line aggregation of financial information and the elimination of intragroup transactions and balances. Particular attention is paid to unrealized gains and losses, intragroup settlements, and the tax implications of consolidation adjustments. Practical approaches are identified for harmonizing accounting policies, performing intragroup reconciliations, and improving the quality of consolidated financial reporting.
International Financial Reporting Standards (IFRS), consolidated financial statements, group of companies, subsidiary, associate, joint venture, goodwill, elimination, statement of cash flows.
As of the date of the study, the preparation of consolidated financial statements (CFS) under Federal Law No. 208-FZ “On Consolidated Financial Statements” is mandatory for public companies, credit institutions, insurance companies and issuers of securities [14]. According to the Bank of Russia and Moscow Exchange, more than 200 Russian issuers disclose IFRS-based consolidated financial statements each year, while the number of groups applying IFRS voluntarily is considerably higher. The practical difficulty lies in the need to apply several standards simultaneously – IFRS 10 Consolidated Financial Statements, IFRS 3 Business Combinations, IAS 28 Investments in Associates and Joint Ventures, IFRS 11 Joint Arrangements and IAS 7 Statement of Cash Flows – each of which establishes its own recognition, measurement and disclosure requirements [9; 10; 11; 12; 15].
Consolidation practice in Russian corporate groups demonstrates a persistent gap between IFRS requirements and the procedures used to implement them in practice. According to assessments published by major audit firms, a significant proportion of material misstatements in consolidated financial statements arises not from errors in underlying accounting records but from incorrect application of consolidation procedures [5]. Therefore, systematising methodological approaches and formalising practical consolidation procedures is particularly important.
The research problem arises from the tension between the increasing complexity of corporate structures and the insufficient formalisation of consolidation algorithms in existing methodological guidance. IFRS 10, IFRS 3, IAS 28 and IFRS 11 establish the relevant principles and disclosure requirements, but they do not provide step-by-step computational procedures tailored, for example, to situations involving inactive markets, multiple settlement currencies and complex logistics chains [9; 10; 11; 12]. As a result, groups often have to develop their own interpretations and working procedures, which may reduce comparability and increase the risk of material misstatement.
An analysis of the scholarly approaches developed in the field of group financial statement consolidation shows that each emphasises a different aspect of the problem. The regulatory approach (A.S. Bakaev, Ya.V. Sokolov; internationally, publications of the IASB and FASB) treats consolidation primarily as the implementation of accounting standards [8]. Within this approach, correct application of IFRS 10, IFRS 3, IAS 28 and IAS 7 is central, whereas the detailed algorithms for eliminations and goodwill calculations remain largely outside the standards and depend on professional judgement. The accounting and analytical approach (V.G. Getman, M.L. Pyatov, E.A. Mizikovsky) focuses on transforming individual financial statement data into an IFRS-compliant format and on the mechanics of line-by-line aggregation [7]. This approach is well developed at the level of an individual entity but is less adapted to multilayer groups with cross-shareholdings. The information-technology approach (Oracle Hyperion Financial Management, 1C: Consolidation) treats consolidation algorithms as an object of automation [6]. The key issue is the formalisation of elimination rules as machine-readable algorithms and the configuration of working adjustment matrices. The institutional approach (agency theory of M. Jensen and W. Meckling; stakeholder theory of R. Freeman) explains the economic rationale for consolidation in terms of reducing information asymmetry between group management and external stakeholders, including investors, creditors and regulators [8].
This study integrates the regulatory and accounting-analytical approaches and complements them with elements of information-technology formalisation. This makes it possible to move from describing IFRS principles to developing specific computational algorithms that can be applied and adapted in consolidation working papers, which constitutes the study’s principal element of novelty.
The methodological basis of the study comprises a combination of general scientific and accounting-specific methods that support a systematic analysis of consolidation processes. The study analyses IFRS requirements, as well as two approaches to measuring non-controlling interests and two approaches to calculating goodwill. The information base consists of the texts of the International Financial Reporting Standards and publications by Russian and international authors on financial statement consolidation.
Under IFRS, a parent and the entities it controls form a group, and consolidated financial statements present the group as a single economic entity [9]. The principal approach to subsidiaries is consolidation on a line-by-line basis. This involves combining the relevant assets, liabilities, equity, income and expenses of the parent and its subsidiaries and subsequently eliminating intragroup transactions and balances.
Control by the parent is therefore the fundamental condition for including an entity within the consolidated group. A subsidiary is an entity controlled by another entity, while a parent is an entity that controls one or more other entities. Accordingly, determining whether control exists is fundamental both to identifying the composition of the group and to selecting the appropriate accounting treatment.
Under IFRS 10 Consolidated Financial Statements, an investor controls an investee when it has power over the investee, exposure or rights to variable returns from its involvement with the investee, and the ability to use its power to affect those returns [9]. Control is therefore not determined solely by the investor’s formal ownership interest; it requires consideration of the nature of the investor’s rights, the decision-making process and the investor’s substantive ability to affect the investee’s returns.
The most common situation is one in which control arises from direct or indirect ownership of more than half of the voting rights. Control may also exist with less than 50% of the voting rights when the investor has the practical ability to direct the relevant activities of the investee. Thus, ownership percentage is not a universal criterion: both the legal rights and their economic substance are important when determining the composition of a group.
Under the consolidation requirements, regardless of the parent’s ownership percentage, the assets and liabilities of a subsidiary are included in the consolidated statement of financial position in full. The same principle applies to the subsidiary’s income and expenses in the consolidated statement of profit or loss and other comprehensive income. Intragroup balances and transactions are eliminated because, from the perspective of the group as a single economic entity, they do not represent transactions with external parties.
One of the principal consolidation adjustments arising from the acquisition accounting requirements of IFRS 3 Business Combinations is the elimination of the parent’s investment in the subsidiary against the subsidiary’s equity and the acquisition-date adjustments arising from the acquisition accounting. The resulting difference is reflected through the recognition of goodwill or a bargain purchase gain, as applicable.
Group retained earnings and other components of equity reflect the parent’s results and the group’s post-acquisition changes in the net assets of its subsidiaries, subject to the applicable consolidation adjustments [10]. It is important to distinguish amounts arising before and after the acquisition date. Pre-acquisition amounts are incorporated into the acquisition accounting and the determination of goodwill or a bargain purchase gain, whereas post-acquisition results contribute to the consolidated financial statements.
When the parent holds less than 100% of a subsidiary, the consolidated financial statements include a non-controlling interest (NCI). NCI represents the portion of the subsidiary’s net assets and results that is not attributable, directly or indirectly, to the parent. NCI is presented separately within equity in the consolidated statement of financial position, while the portion of profit or loss and other comprehensive income attributable to NCI is presented separately in the relevant components of the consolidated financial statements.
In preparing consolidated financial statements, three fundamentally different situations must be distinguished: control over a subsidiary, significant influence over an associate, and joint control over a joint venture. Subsidiaries are consolidated, whereas investments in associates and joint ventures are generally accounted for using the equity method. This distinction determines the consolidation procedures, the recognition of financial results and the presentation of investments in the consolidated financial statements.
An associate is an entity over which the investor has significant influence but which is neither a subsidiary nor a joint venture of the investor. Significant influence is the power to participate in the financial and operating policy decisions of the investee without having control or joint control. Indicators may include representation on the board of directors or a similar governing body, participation in policy-making processes, material transactions between the investor and the investee, interchange of managerial personnel and provision of essential technical information.
IFRS uses direct or indirect ownership of 20% or more of the voting power as a general presumption of significant influence. Such an interest creates a rebuttable presumption of significant influence, but it is not conclusive in every case. Conversely, ownership of less than 20% does not preclude significant influence when other circumstances support its existence.
Because an associate is not controlled by the investor, its assets, liabilities, income and expenses are not included line by line in the investor’s consolidated financial statements. Instead, the investment is accounted for using the equity method. On initial recognition, the investment is recognised at cost; subsequently, its carrying amount is adjusted for the investor’s share of changes in the investee’s net assets after acquisition. In particular, the carrying amount increases by the investor’s share of the investee’s profit or loss and other comprehensive income and decreases by dividends received.
A joint venture is a joint arrangement in which the parties that have joint control have rights to the net assets of the arrangement. Joint control is contractually agreed and exists only when decisions about the relevant activities require the unanimous consent of the parties sharing control.
Investments in joint ventures are generally accounted for by the investor using the equity method in accordance with IFRS. Accordingly, the joint venture’s assets, liabilities, income and expenses are not included line by line in the investor’s consolidated financial statements. Instead, the consolidated statement of financial position presents the carrying amount of the investment, adjusted for the investor’s share of changes in the joint venture’s net assets, while the consolidated statement of profit or loss and other comprehensive income recognises the investor’s share of the joint venture’s financial results.
IFRS 12 requires disclosure of information about interests in joint ventures, the nature of the relationship with them and the effects and risks associated with those interests. Such information enables users to assess the nature of the group’s involvement and the effects of its interests on the group’s financial position, financial performance and cash flows.
Accounting for the acquisition of a subsidiary that constitutes a business combination is particularly important under IFRS 3 Business Combinations. The identifiable assets acquired and liabilities assumed are determined as of the acquisition date and, subject to the exceptions specified in IFRS 3, are measured at their acquisition-date fair values. This approach is important in practice because it allows the consolidated financial statements to recognise assets and liabilities that may not have been recognised in the acquiree’s separate financial statements.
Under the acquisition method, identifiable intangible assets that were not previously recognised by the acquiree may be recognised separately when they meet the relevant recognition criteria. Examples include certain contractual rights, customer relationships and technologies. Thus, consolidation reflects not only the legal form of an acquisition of shares or interests but also the economic substance of the acquired business.
Goodwill represents the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognised. Accordingly, determining goodwill requires comparing the acquisition-date consideration and other components specified by IFRS 3 with the fair value of the identifiable net assets acquired.
For a business combination, goodwill is generally measured as the excess of the consideration transferred, the amount of any non-controlling interest in the acquiree, and, in a business combination achieved in stages, the acquisition-date fair value of any previously held equity interest over the acquisition-date fair value of the identifiable net assets acquired. If, after the required reassessment, the fair value of the identifiable net assets acquired exceeds the aggregate of those amounts, a bargain purchase gain is recognised in profit or loss.
The basis for subsequent consolidation is established at the acquisition date. The acquisition-date fair values of the identifiable net assets, goodwill or any bargain purchase gain, and the NCI are determined at that point.
Tax effects require particular attention when preparing consolidated financial statements. If the fair value measurement of assets acquired and liabilities assumed gives rise to temporary differences between their carrying amounts for financial reporting purposes and their tax bases, IAS 12 Income Taxes requires recognition of the relevant deferred tax assets or liabilities, subject to the applicable recognition requirements and exceptions. Such adjustments affect the recognised net identifiable assets acquired and may therefore affect the measurement of goodwill.
The economic substance of goodwill may be associated with expected synergies from the combination, market position, the assembled workforce, reputation and other factors. However, these benefits cannot always be individually identified and recognised as separate assets [4].
When the parent holds less than 100% of a subsidiary, NCI arises in the consolidated financial statements. It represents the portion of the subsidiary’s equity and results that is not attributable, directly or indirectly, to the parent. The subsidiary’s assets, liabilities, income and expenses are nevertheless included in full, while the amount attributable to NCI is presented separately within equity and in the allocation of profit or loss and other comprehensive income.
IFRS 3 provides two measurement options for NCI at the acquisition date for each business combination. For qualifying present ownership interests, NCI may be measured either at fair value or at the proportionate share of the acquiree’s recognised identifiable net assets. The choice affects the amount of goodwill recognised at the acquisition date.
When NCI is measured at its proportionate share of the acquiree’s recognised identifiable net assets, only the goodwill attributable to the parent is recognised. When NCI is measured at fair value, the consolidated financial statements recognise full goodwill, including the portion attributable to NCI.
For a transaction in which control is obtained in a single acquisition, the calculation may be presented as follows:
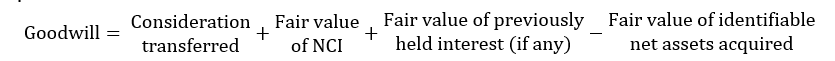
(1)
In subsequent periods, the carrying amount of NCI changes to reflect the NCI holders’ share of changes in the subsidiary’s net assets after the acquisition date, together with other changes required by IFRS.
After initial recognition, goodwill is not subsequently remeasured through ordinary periodic revaluation. Instead, goodwill is tested for impairment in accordance with IAS 36 Impairment of Assets at least annually and whenever there is an indication that it may be impaired. If an impairment loss is identified, it is recognised in profit or loss, subject to the requirements of IAS 36 [13].
Goodwill at the reporting date may be expressed in a simplified calculation as follows:
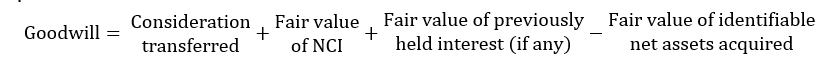
(2)
Accordingly, when control of a subsidiary is lost, the goodwill allocated to the subsidiary is taken into account in determining the gain or loss on the disposal and deconsolidation.
It should again be emphasised that the consolidated statement of financial position presents the financial position of the group as a single economic entity. The assets and liabilities of the parent and its subsidiaries are included in full, after which intragroup balances and transactions are eliminated. These include, for example, reciprocal receivables and payables, intragroup loans, balances arising from intragroup sales, income and expenses from transactions between group entities, and the parent’s investment in subsidiaries.
At the first stage, corresponding line items of the parent and subsidiaries are aggregated line by line. A subsidiary is included in the consolidated financial statements in full from the date control is obtained, regardless of the percentage of its equity owned by the parent. Ownership of less than 50% is not, by itself, a basis for proportionately reducing the subsidiary’s assets, liabilities, income or expenses.
The next stage is the elimination of the parent’s investment in the subsidiary against the subsidiary’s equity and the acquisition-date adjustments arising from the acquisition accounting.
Intragroup financial receivables and payables are also eliminated. If the parent has provided a loan to a subsidiary, the parent’s receivable and the subsidiary’s corresponding liability are eliminated from the consolidated statement of financial position. The same applies to intragroup loans, deposits and other reciprocal financial balances.
Reciprocal receivables and payables arising from intragroup sales of goods or services are likewise eliminated in full. After consolidation, neither balance remains because the group cannot be regarded as both creditor and debtor to itself.
The same principle applies to intragroup advances. If one group entity has received an advance from another, the corresponding receivable and payable are eliminated. Where the balances differ, their economic cause should be identified and the appropriate consolidation adjustment determined rather than automatically charging the difference to retained earnings.
Intragroup dividends are also eliminated. Dividend income recognised by the parent from a subsidiary does not represent income of the group because the distribution occurs within a single economic entity. If dividends have been declared but not yet paid, the corresponding intragroup receivable and payable balances are also eliminated.
Transactions involving assets may give rise to unrealised gains or losses. If one group entity sells goods, property, plant and equipment or other assets to another group entity at a profit and the asset remains within the group at the reporting date, the profit is not yet realised from the group’s perspective. The relevant profit or loss is therefore adjusted for the unrealised amount, and the carrying amount of the asset is adjusted to the amount that should be recognised from the group’s perspective.
If eliminating an unrealised profit creates a temporary difference between the carrying amount of the asset in the consolidated financial statements and its tax base, the relevant deferred tax asset or liability is recognised in accordance with IAS 12, subject to the standard’s requirements [16].
The consolidated statement of profit or loss and other comprehensive income is prepared from the results of the parent and the subsidiaries included in the group. A subsidiary’s income and expenses are included in full from the date control is obtained until the date control is lost. The results of intragroup transactions are eliminated because, from the group’s perspective, they do not represent income or expenses arising from transactions with external parties.
A principal step in preparing the statement is the line-by-line aggregation of the relevant income and expenses of the parent and its subsidiaries. This is followed by consolidation adjustments eliminating intragroup revenue and related expenses, income and expenses from intragroup services and other transactions, intragroup dividends, and unrealised gains and losses included in the carrying amounts of assets that remain within the group at the reporting date.
One of the principal adjustments is the elimination of dividends received by the parent from a subsidiary. Such dividends may be recognised as income in the parent’s separate financial statements, but they do not constitute external income of the group because they represent a distribution of profit within a single economic entity.
Similarly, income and expenses arising from sales of goods or services between group entities are eliminated. Because no sale to an external party has occurred at the group level, the corresponding intragroup income and expenses are eliminated. If the transferred asset remains wholly or partly within the group at the reporting date, any unrealised gain or loss included in its carrying amount is also eliminated.
The group’s final profit or loss is allocated between owners of the parent and NCI. Because the subsidiary is consolidated in full, its profit or loss is initially included in the group’s result in full. After all necessary consolidation adjustments, the portion attributable to owners of the parent and the portion attributable to NCI are determined. The parent’s share of the subsidiary’s profit or loss is therefore not obtained by simply multiplying the subsidiary’s separate profit by the parent’s ownership percentage, because intragroup transactions, unrealised gains and losses and other consolidation adjustments must also be taken into account.
Similar procedures are performed for each subsidiary, including the elimination of intragroup transactions between subsidiaries themselves.
Income and expenses of a subsidiary are included in the consolidated statement only for the period during which the group controls the subsidiary. From the date control is lost, the former subsidiary is no longer consolidated.
When control of a subsidiary is lost, the group recognises the resulting gain or loss on the loss of control [1]. The calculation takes into account the consideration received, the carrying amount of the former subsidiary’s net assets, including related goodwill, and the corresponding NCI. The resulting difference is recognised in profit or loss in accordance with IFRS requirements.
The elimination procedures considered above apply to different types of intragroup transactions and affect several components of the consolidated financial statements. Table 1 summarises the main elimination objects, the affected financial statement line items and the substance of the corresponding procedures.
Table 1.
Algorithms for eliminating intragroup transactions in the preparation of consolidated financial statements
| Consolidation adjustment (intragroup transaction) | Affected CFS line items | Elimination algorithm (substance of the adjustment in working papers) |
| Investment in subsidiaries and subsidiary equity | Investment in subsidiaries / Equity | Eliminate the parent’s investment against the subsidiary’s equity and acquisition-date adjustments, with the resulting amount reflected through goodwill or a bargain purchase gain, as applicable. |
| Intragroup trade receivables and payables | Trade and other receivables / Trade and other payables | Eliminate reciprocal balances in full. Differences caused by timing, uninvoiced deliveries or other reconciling items should be investigated and adjusted based on their economic substance rather than automatically charged to retained earnings. |
| Intragroup sales of goods and services | Revenue / Cost of sales (profit or loss) | Eliminate intragroup revenue and the corresponding expenses for the period to prevent the group from recognising internal transactions as external activity. |
| Unrealised profit in inventories | Inventories / Relevant profit or loss and equity effects | Reduce inventories by the unrealised intragroup margin remaining at the reporting date and recognise the related tax effect when required by IAS 12. |
| Intragroup dividends | Dividend income / Equity distribution | Eliminate dividend income recognised by the parent against the corresponding distribution recognised by the subsidiary; eliminate any related intragroup receivable and payable if the dividend remains unpaid. |
| Intragroup loans and interest | Current/non-current borrowings / Interest income and expense | Eliminate intragroup loan balances and the related interest income and expense. Any reconciling difference should be investigated and adjusted according to its nature. |
| Advances paid and received | Other current assets / Other current liabilities | Eliminate reciprocal intragroup advance balances after reconciling differences. |
| Intragroup cash flows | Operating / Investing / Financing activities | Eliminate reciprocal cash receipts and payments between group entities so that only cash flows with external parties remain. |
| Non-controlling interest | Equity / Profit or loss and other comprehensive income | Determine and present the NCI in the subsidiary’s net assets and in the allocation of the group’s financial result. |
The procedures presented above form the basis of a working consolidation algorithm and should be performed with regard to the nature of each intragroup transaction and its effect on the relevant financial statement line items.
The statement of cash flows is another component of the consolidated financial statements. Its preparation is governed by IAS 7 Statement of Cash Flows [15]. Unlike the statement of financial position and the statement of profit or loss and other comprehensive income, it presents the inflows and outflows of cash and cash equivalents during the reporting period.
IAS 7 permits cash flows from operating activities to be presented using either the direct or the indirect method. Under the direct method, major classes of gross cash receipts and payments are disclosed. Under the indirect method, profit or loss is adjusted for non-cash transactions, changes in working capital, accruals and other items whose effects relate to different periods or to investing or financing activities. For reporting periods to which the IFRS 18 amendments to IAS 7 apply, the indirect method starts from operating profit or loss [15].
Cash flows are classified into three activities: operating activities, which comprise the principal revenue-producing activities and other activities that are not investing or financing activities; investing activities, which relate to the acquisition and disposal of long-term assets and other investments not included in cash equivalents; and financing activities, which result in changes in the size and composition of contributed equity and borrowings.
When preparing a consolidated statement of cash flows, reciprocal cash flows between group entities must be taken into account. Intragroup cash receipts and payments should not distort information about the group’s cash flows as a whole. Therefore, internal cash flows between the parent and subsidiaries and between subsidiaries themselves are eliminated. Only cash flows involving external parties remain in the consolidated statement.
A different approach applies to investments in associates and joint ventures accounted for using the equity method. The investee’s cash flows are not included line by line in the investor’s statement of cash flows. Instead, the consolidated statement reflects actual cash transactions between the investor and the investee, such as dividends received, loans provided or repaid, and other cash receipts and payments.
When a subsidiary is acquired, the related cash flow is classified as investing and is based on the cash consideration actually paid, net of cash and cash equivalents acquired with the business. The net cash outflow is therefore calculated as the cash consideration paid less the cash and cash equivalents held by the acquired subsidiary at the acquisition date. Non-cash consideration, such as the issue of shares by the parent, is excluded from cash flows but is disclosed separately in accordance with IAS 7.
When a subsidiary is disposed of, the related cash flow is likewise classified as investing. It is determined as the cash consideration received by the group less the cash and cash equivalents disposed of with the subsidiary. If the group retains an interest in the former subsidiary after losing control, subsequent accounting depends on the nature of the retained rights and the applicable IFRS requirements.
The analysis of methodological approaches and practical consolidation algorithms makes it possible to formulate a number of recommendations aimed at improving the quality, comparability and reliability of consolidated financial statements.
- Harmonisation of accounting policies and the corporate chart of accounts. Before consolidation, the group should ensure consistent accounting policies for like transactions across all entities within the consolidation perimeter, in accordance with IFRS 10 and the applicable requirements of other IFRS Accounting Standards [9]. Particular attention should be paid to inventory measurement, revenue recognition, depreciation and financial instruments. To accelerate consolidation and reduce the risk of errors, it is advisable to use a common corporate chart of accounts or a centralised mapping matrix linking entity-level accounts to the consolidation structure. This provides a consistent information base for line-by-line aggregation.
- Formalisation of intragroup reconciliations. Reciprocal balances should be checked not only when annual financial statements are prepared but also on a regular basis. Monthly or quarterly reconciliation of intragroup transactions and balances should be established, with differences documented before the preparation of entity-level financial statements [2]. This helps identify discrepancies caused by uninvoiced deliveries, payments in transit, differences in transaction recognition dates and other factors that may affect the consolidated financial statements.
- Automation of goodwill and NCI calculations. Business combination accounting, subsequent impairment testing of goodwill under IAS 36 and determination of NCI require substantial amounts of source data and are repeated in subsequent reporting periods. It is therefore advisable to use specialised CPM/EPM solutions capable of storing acquisition-date calculations, automatically incorporating changes in net assets and generating the required analytical reconciliations [6]. This is particularly important for groups with several subsidiaries and complex ownership structures.
- Accounting for the tax effects of consolidation adjustments. Adjustments made only at the consolidated financial statement level may create temporary differences between the carrying amounts of assets and liabilities and their tax bases. This is particularly relevant to the elimination of unrealised profits on intragroup transactions and fair value adjustments arising from business combinations. Accordingly, each material consolidation adjustment should be assessed for its tax effect under IAS 12, and deferred tax assets or liabilities should be recognised when the relevant requirements are met [16]. Changes in these balances should also be monitored in subsequent reporting periods.
In conclusion, IFRS-based consolidation is a structured sequence of procedures that includes determining the group perimeter and whether control exists, accounting for business combinations, measuring goodwill and NCI, aggregating financial statement information and eliminating intragroup transactions. The quality of the resulting financial statements depends not only on the accuracy of individual calculations but also on the consistency of accounting data across all entities in the group.
Improving the efficiency of consolidation primarily requires formalised procedures, regular intragroup reconciliation, harmonised accounting approaches and the use of automated tools. Implementing these recommendations can reduce the number of manual adjustments, identify discrepancies at an earlier stage and improve the reliability of consolidated financial statements prepared for users in accordance with IFRS Accounting Standards.
References
1. Komarova, M.A., Yazykova, S.V., & Plekhanova, E.O. (2022). Problemy ucheta i formirovaniya konsolidirovannoy otchetnosti korporatsiy pri potere kontrolya nad dochernimi i assotsiirovannymi kompaniyami // Biznes. Obrazovanie. Pravo, 4(61), 146-152.
2. Blizkiy, R.S., Lisitsyna, Yu.A., & Dubeshko, D.N. (2023). Model protsedur konsolidatsii finansovoy otchetnosti s uchetom transformatsiy MSFO // Upravlencheskiy uchet, 12-2, 394-403.
3. Babalykova, I.A., Bogosyan, A.I., & Korotkova, V.I. (2024). Osobennosti formirovaniya finansovoy otchetnosti gruppy kompaniy // Estestvenno-gumanitarnye issledovaniya, 3(53), 29-32.
4. Kuvaldina, T.B. (2025). Gudvil kak obekt bukhgalterskogo ucheta i element konsolidirovannoy (finansovoy) otchetnosti // Innovatsionnaya ekonomika i obshchestvo, 2(48), 48-55.
5. Bekbuzarova, M.I. (2025). Audit konsolidirovannoy finansovoy otchetnosti po MSFO: problemy i resheniya // Vestnik evraziyskoy nauki, 17(S2).
6. Zherdeva, O.V., Cherstova, A.V., Eskova, T.V., & Kashina, M.I. (2024). Tsifrovaya transformatsiya finansovoy otchetnosti: rol MSFO v sovremennom biznese // Vestnik Akademii znaniy, 6(65), 363-366.
7. Litvinenko, M.I. (2024). Konsolidirovannaya finansovaya otchetnost v sootvetstvii s MSFO / Moscow: Yurayt. 126 p.
8. Alisenov, A.S. (2024). Mezhdunarodnye standarty finansovoy otchetnosti (prodvinutyy kurs) / Moscow: Yurayt. 443 p.
9. IFRS Foundation. (2026). IFRS 10 Consolidated Financial Statements. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ifrs-10-consolidated-financial-statements/ (accessed: September 10, 2026).
10. IFRS Foundation. (2026). IFRS 3 Business Combinations. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ifrs-3-business-combinations/ (accessed: September 10, 2026).
11. IFRS Foundation. (2026). IAS 28 Investments in Associates and Joint Ventures. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ias-28-investments-in-associates-and-joint-ventures/ (accessed: September 10, 2026).
12. IFRS Foundation. (2026). IFRS 11 Joint Arrangements. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ifrs-11-joint-arrangements/ (accessed: September 10, 2026).
13. IFRS Foundation. (2026). IAS 36 Impairment of Assets. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ias-36-impairment-of-assets/ (accessed: September 10, 2026).
14. Federal Law No. 208-FZ of July 27, 2010 “On Consolidated Financial Statements” (as amended April 9, 2026). Available at: https://www.consultant.ru/document/cons_doc_LAW_103808/ (accessed: September 10, 2026).
15. IFRS Foundation. (2026). IAS 7 Statement of Cash Flows. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ias-7-statement-of-cash-flows/ (accessed: September 10, 2026).
16. IFRS Foundation. (2026). IAS 12 Income Taxes. Available at: https://www.ifrs.org/issued-standards/list-of-standards/ias-12-income-taxes/ (accessed: September 10, 2026).